Borrow Money: Fast Cash Loan
- 4.7
- Rating
- 100.00K
- Installs
- Free
- Price
 Analysis by App-foxy
When an unexpected bill lands between paydays, the difficult part is often not finding a borrowing app; it is deciding whether a quick advance will genuinely solve the problem or simply move the pressure to a later date. I approached Borrow Money: Fast Cash Loan with that question in mind. It is a free finance app from Dollar Loan Center that focuses on connecting people with a cash advance, including applicants who may have poor credit. That makes it relevant for a narrow but important situation: a short-term gap where timing matters more than finding the cheapest long-term borrowing option.
My overall impression is that the app is built around speed and a straightforward purpose rather than financial education or full money management. It is not a budgeting dashboard, a savings coach, or a replacement for a bank account. Its value depends on what happens after you enter your information, review the available terms, and decide whether the repayment obligation fits your next income cycle. The most important feature is not getting to an offer quickly; it is being able to judge that offer calmly before accepting it.
From a sudden cash gap to a borrowing decision
I start with the moment that makes a cash advance tempting: an urgent bill, a tight deadline, and too little room in the budget. This section looks at how to turn that pressure into a deliberate borrowing decision, including the practical checks I would make before opening an application. From there, I’ll consider what the app’s speed can and cannot mean once a request is underway.
You May Also Like

 Blood Strike: 2.5 Anniversary
Blood Strike’s Loadouts Turn Every Drop Into a Tactical Gamble
A close look at Blood Strike’s custom loadouts: how fast access to signature weapons reshapes its battle royale rhythm, rewards preparation, and narrows the gap between fights.

 Pandora - Music & Podcasts
Pandora’s Music Is Easy to Start, but Harder to Recover
Pandora’s strength is its low-effort path from a seed to a station. Its weak spot is how much confidence it asks you to place in connection, setup, and quiet recovery.

 8 Ball Pool
 Is Built on Rivalries, Rematches, and Routine
A close look at the rivalries, rematches, shared routines, and unanswered safety questions that turn a quick pool match into a persistent mobile community.

 Samsung Music
’s Quiet Strength Is Playing What You Already Own
Its reach comes less from spectacle than from dependable access to a personal library. That simplicity is both the app’s strongest retention engine and its ceiling.

 AccuWeather: Weather Radar
AccuWeather Review: A Quick, Clear Forecast for Everyday Decisions
For everyday plans, the best forecast is the one you can understand quickly. AccuWeather makes rain timing, radar, and local conditions easy to act on, with a few trade-offs.

 Hill Climb Racing
Why Hill Climb Racing Still Turns Crashes Into One More Run
A tiny car, a bumpy hill and one more upgrade: Hill Climb Racing keeps resurfacing because its simple chaos makes every near-miss feel personal.
More From Our News Desk
View All News


Starting with the problem, not the app
A realistic use case would be a household facing a necessary expense shortly before payday. Perhaps a utility payment is due, a car is needed for work, or a prescription cannot wait. In that moment, a conventional bank loan may feel too slow or inaccessible, especially for someone with a limited or damaged credit history. Borrow Money: Fast Cash Loan is aimed at that pressure point, offering a mobile route to request a cash advance instead of beginning with a branch visit or a lengthy search across lenders.
That convenience is also where I would set my first boundary. I would only consider using this kind of service for a defined, one-time need with a clear repayment source. I would not use it to cover ordinary spending, another loan payment, or a recurring shortfall. If the same expense will appear again next month, a fast advance treats the symptom while leaving the underlying problem untouched.
The app’s store rating is a 4.7 average from around 21 thousand ratings, and it has passed 100 thousand installs. Those figures suggest that many people find the basic borrowing journey useful, but they do not tell me whether a particular offer will suit my circumstances. A high user rating cannot replace reading the amount to repay, the timing, and any conditions shown during the application.
What I would prepare before opening it
The smoothest workflow starts before the first screen. I would have a dependable internet connection, a current view of my bank balance, and a written figure for the exact amount needed. Asking for more than the bill requires can make repayment harder, while asking for too little may leave the original problem unresolved and encourage a second application.
I would also decide in advance what income will repay the advance and on which date. This is a small but useful discipline: instead of thinking “I can probably manage it,” I would compare the expected repayment with rent, food, transport, utilities, and other fixed commitments. The app can help begin the request, but it cannot make an unaffordable repayment affordable.
Because this is a finance app, I would treat every personal and banking detail as consequential. I would check that I am using the official application published by Dollar Loan Center, read each screen rather than tapping through automatically, and avoid starting the process on a shared device. I would also keep a record of the final terms shown to me. That record is useful later if I need to compare the repayment with my bank statement.
The first stage of the mobile flow
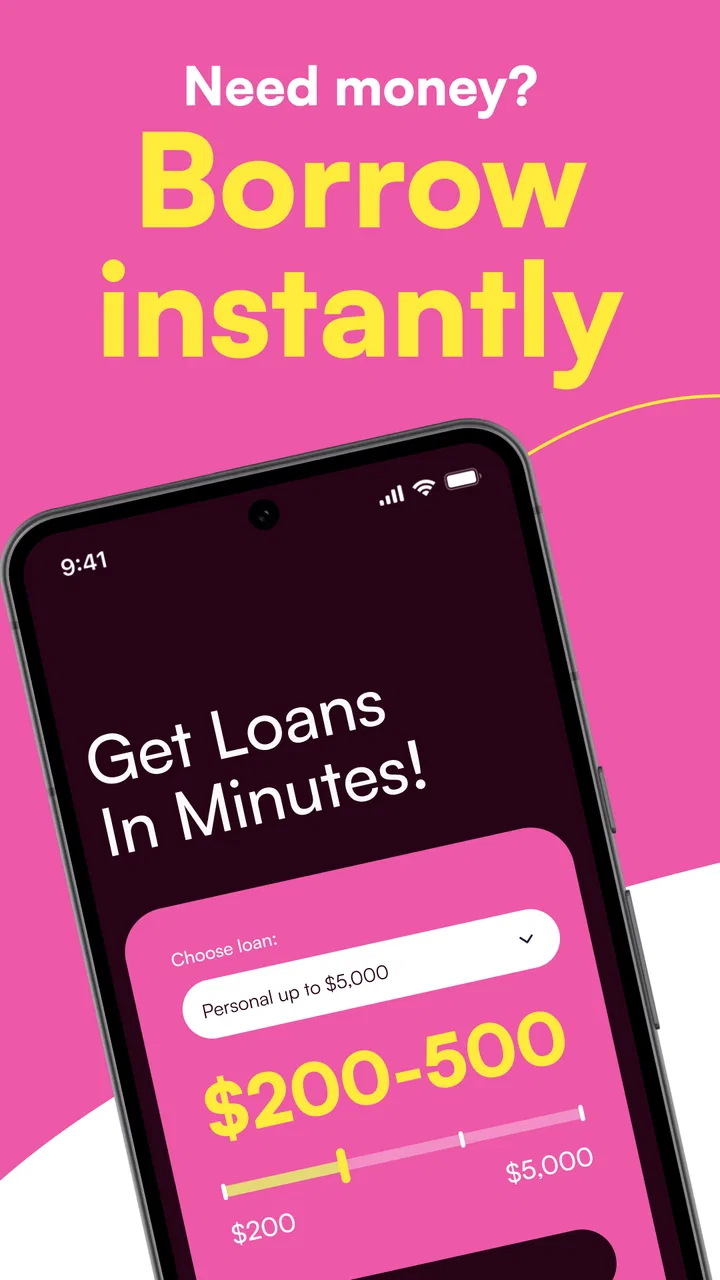
Opening the app takes me into a purpose-built borrowing experience rather than a broad collection of financial tools. The central task is to request money, so the interface should be approached as an application rather than a calculator or general-purpose wallet. I would expect the process to ask for information needed to assess the request and to move through several verification steps before any outcome is reached.
One practical tip is to separate “starting an application” from “accepting an offer.” Those are not the same decision. Beginning the process may help show what is available, but I would not treat the appearance of a possible amount as approval, and I would not assume that the first screen represents the final cost. The handoff from entering details to reviewing terms is the point where I would slow down.
The current version is 0.2.2, and the app runs on Android 7.0 or later. That broad compatibility is helpful for people using older Android phones, although compatibility alone does not guarantee that every device will feel equally responsive. I would keep the operating system updated where possible and make sure the phone has enough battery to finish an application without interruption.
Information handoffs and moments that deserve attention
The most important handoff is between the app and the lending process behind it. The app is the front door, but the final decision is not something I would interpret as being created solely by the interface. Information entered on the phone has to be reviewed, and the result may depend on the applicant’s circumstances. That means a fast-looking screen does not necessarily mean an instant or guaranteed outcome.
A second handoff occurs when the app presents the borrowing terms. At that stage, I would look beyond the amount offered and focus on the total repayment, the due date, and any charges or conditions displayed. The amount deposited can feel like the main number because it solves the immediate problem, but the amount leaving my account later is the number that determines whether the decision was sensible.
I would also watch for requests to verify identity, income, or account information. These steps can feel like friction when someone is already stressed, yet they are precisely where careless mistakes can create problems. I would enter details consistently, check spelling and account numbers, and avoid switching between multiple applications while the process is open. A mismatch can delay the outcome or require the process to be repeated.
What the app is good at in everyday use
Its clearest strength is focus. Someone looking specifically for a short-term cash advance does not have to navigate a full banking suite before reaching the relevant task. The app’s positioning also acknowledges a group often excluded from conventional borrowing: people with bad credit. That does not mean every applicant will receive money, but it does make the product more relevant than a traditional bank application for users who already know their credit history may be a barrier.
The mobile format is useful when the problem happens outside business hours or when visiting a lender is impractical. A person dealing with a payment deadline can begin from a phone and keep the process connected to the situation that prompted it. I see that as a convenience, not a reason to skip comparison. A fast application is valuable only if the resulting obligation is understandable.
Another strength is that the app is free to install and rated for Everyone, which lowers the initial barrier to trying the service. The age classification should not be confused with eligibility to borrow; financial agreements still involve requirements that an individual must meet. I would regard the rating as information about the app’s general audience, not as a promise that every adult can qualify.
Where it differs from usual alternatives
Compared with a bank or credit union, this app is more appealing when speed and access matter more than an established relationship with a financial institution. A bank may offer a broader range of products or potentially more suitable longer-term borrowing, but its application process may not fit a small, urgent gap. A credit union can be a better place to investigate lower-cost borrowing if I have time and membership access.
Compared with a credit card, a cash advance may avoid adding another revolving line, but the repayment structure can be less forgiving if the due date arrives before the next budget cycle is ready. Compared with borrowing from family or friends, the app offers privacy and a formal process, while personal borrowing may involve less financial cost but more relationship pressure. Compared with overdraft protection, it may be easier to understand a separate advance, though the right choice depends on the terms and the account involved.
These comparisons lead to a useful rule: I would use the app to investigate an option, not to assume it is automatically better than every alternative. If the expense can wait, I would first consider postponing it, negotiating a payment date, using existing savings, or finding a lower-cost source. If the need is large or ongoing, I would look for structured credit counseling or a longer-term solution instead of repeating short advances.
Reading the result carefully
The outcome I would want is not simply a message saying that money is available. I would want a complete picture of how much I receive, how much I must repay, and when the repayment will occur. If any part of that picture is unclear, I would stop before accepting anything. A few minutes spent understanding the obligation is more valuable than a few minutes saved during the application.
Once a decision is made, I would immediately update my personal budget. I would mark the repayment date, reserve the expected amount, and reduce optional spending until the obligation is cleared. This is one of the less obvious but most important parts of the workflow: the app may finish when the funds become available, but the user’s responsibility continues beyond that screen.
I would also watch my bank account around the expected transfer and repayment dates. If the money does not appear when expected, or if a repayment looks different from what I recorded, I would contact the appropriate support channel promptly and keep screenshots or confirmation details. Treating the transaction as something to monitor, rather than a one-tap event, gives me a better chance of catching a problem early.
Where the flow can break down
The first possible break is eligibility. The app’s promise of access for people with bad credit makes it attractive, but it should not be read as guaranteed approval. An application can still lead to an outcome that does not meet the requested amount or does not fit the applicant’s circumstances. I would avoid making an urgent purchase based on money that has not actually been approved and made available.
The second break is affordability. Even a successful application can be the wrong result if the repayment consumes money needed for essentials. This is especially risky when the user focuses on the cash received and mentally postpones the repayment. I would calculate the post-repayment budget before accepting, not after the transfer arrives.
There can also be practical friction during identity or account verification. Incorrect information, an outdated bank account, a weak connection, or an interrupted session can turn a supposedly quick process into a frustrating one. My workaround would be simple: use accurate details, complete the application in one sitting, and avoid relying on the advance until the outcome is confirmed.
Finally, the app is not the right tool for every financial emergency. I would skip it if I need a large amount, if I cannot identify a reliable repayment date, or if I am already juggling several short-term debts. In those cases, speaking with a credit counselor, contacting the bill provider, or comparing a more structured loan would be safer than adding another fast obligation.
Who I would recommend it to
I would recommend considering Borrow Money: Fast Cash Loan to an adult who has a specific short-term cash gap, understands that approval is not automatic, and can repay the full obligation from a known upcoming income source. It is particularly relevant for someone whose credit history makes a conventional bank route less practical and who needs to begin the process from a phone.
I would not recommend it as a routine way to stretch a paycheck. I would also be cautious about using it for discretionary purchases, repeated bills, or debt repayment. Those situations suggest a broader cash-flow problem, and a sequence of advances can make that problem harder to see. The app can be useful at the edge of a temporary emergency, but it should not become part of the monthly budget.
For people deciding whether to install it, the cost of entry is low because the app is free, and its compatibility with Android 7.0 or later makes it accessible on many older devices. Its developer is Dollar Loan Center, and the app was released on August 6, 2024. I would still judge it on the terms shown during my own application rather than on its age, download count, or rating.
My final take after following the workflow
Borrow Money: Fast Cash Loan is best understood as a focused doorway to a short-term cash advance, not as a complete financial safety net. I like the way its purpose is clear, and I can see why its mobile approach appeals to people who need to explore borrowing quickly, including those with poor credit. The strong user response and more than a thousand reviews indicate that it has found an audience, but popularity does not remove the need for careful reading.
My recommendation is conditional but positive: use it only when the need is genuine, the amount is limited, and repayment is already mapped out. Move slowly at the handoff from application to terms, record the final obligation, and monitor the account afterward. If the repayment would leave essentials uncovered, or if the same crisis is likely to return, a bank, credit union, bill negotiation, savings plan, or professional debt advice may be a better direction.
In my view, the app succeeds when it helps someone evaluate a temporary option without wasting time, and fails when speed encourages a decision that the next paycheck cannot support. That distinction is the key to using it responsibly.
FAQs for Borrow Money: Fast Cash Loan
01What is Borrow Money: Fast Cash Loan, and how does it work?
Borrow Money: Fast Cash Loan is a financial app designed to help users explore short-term borrowing options through a mobile device. After creating an account, you may be asked to provide personal, employment, income, and banking information so the service can assess eligibility. Available loan amounts, repayment periods, interest rates, and approval decisions can vary by applicant and location.
02Is Borrow Money: Fast Cash Loan a direct lender?
Before applying, check whether Borrow Money: Fast Cash Loan provides loans directly or operates as a lender-matching and lead-generation service. Some apps collect application details and share them with third-party lenders or financial partners. Read the app’s terms, privacy policy, and disclosures carefully to understand who may contact you, who makes the lending decision, and what fees or obligations may apply.
03How much does borrowing through the app cost?
The total cost can include an annual percentage rate, interest, origination charges, late-payment fees, or other service costs, depending on the lender and your agreement. Do not rely only on the advertised loan amount or repayment estimate. Review the complete offer before accepting, including the total repayment, payment schedule, due dates, and consequences of missing a payment.
04What information and permissions does the app require?
A loan application may request identity details, contact information, employment and income data, bank information, and permission to verify certain records. Only provide information through the official app or a secure website, and avoid granting unnecessary device permissions. Reviewing the privacy policy is important because submitted data may be processed or shared with lenders, service providers, or marketing partners.
05Is Borrow Money: Fast Cash Loan safe and available to everyone?
Availability and eligibility depend on your country, state or region, age, income, credit profile, and the participating lender’s requirements. Download the app only from an official store, verify the developer, and look for clear contact and licensing information. A legitimate service should not guarantee approval or demand unusual upfront payments to release a loan. Borrow only what you can comfortably repay.
Pros
- Simple application process with minimal paperwork required.
- Quick eligibility checks can save time in urgent situations.
- Loan details are presented clearly before applying.
- Useful repayment reminders may help avoid missed due dates.
- Available from a mobile device without visiting a branch.
Cons
- Approval and loan availability may depend on your location.
- Interest rates and fees can be high compared with traditional loans.
- Late payments may lead to additional charges or collection contact.
- The app may request access to sensitive personal information.
- Borrowing repeatedly can make it harder to manage your finances.

Borrow Money: Fast Cash Loan
Gallery